
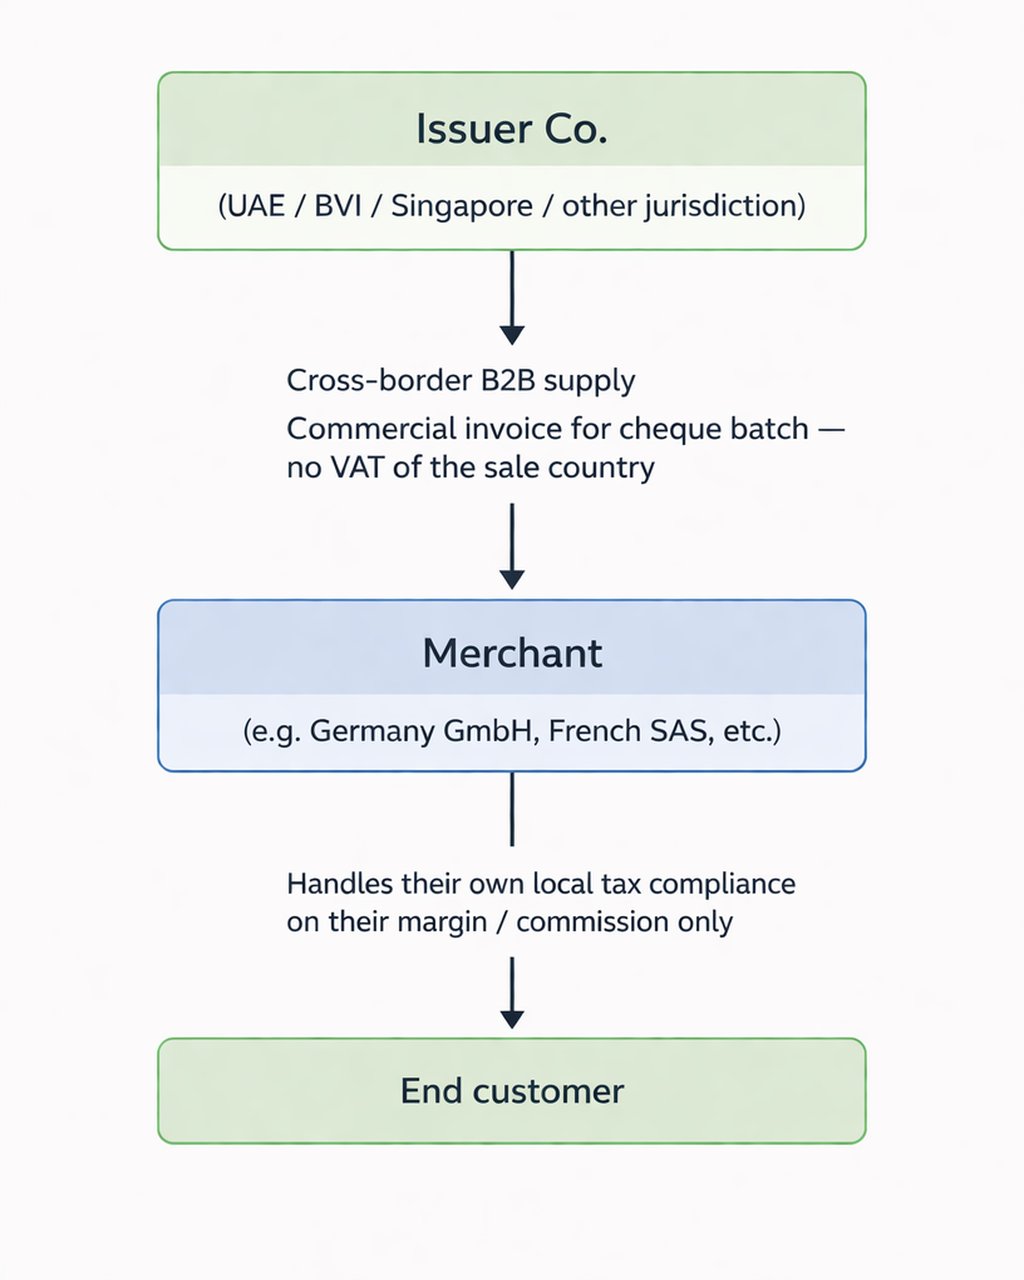
Why This Works for VAT
- Cross-border B2B supply from a non-resident entity means the issuer does not register for VAT in the merchant’s country.
- In the EU context, the reverse charge mechanism applies where relevant. The merchant self-accounts if applicable, but only on the value of the service they receive, not on the cheque face value they resell.
- The issuer pays taxes only in its own jurisdiction on its own margin or revenue.
- Merchants are responsible for their own local tax compliance. This is outside the platform scope.
Note: The platform does not classify USDC cheques as financial instruments for the purpose of this model, at least in the initial phase. The cheque is treated as a commercial product, similar to a digital prepaid card. Financial instrument classification may be revisited later as the product matures and regulatory clarity emerges in specific jurisdictions.